Company News, Deals
From April 2025, new regulations increasing company size thresholds and removing certain requirements from the Directors’ report will be effective.
The uplift is part of a drive to cut complexity and reduce the reporting burden on companies. It accounts for the impact of inflation since the thresholds were set in 2013. Unfortunately there will be limited impact of these changes for charities: Charities will still be required to report under FRS 102, and therefore even if they fall under the thresholds of the micro entity regime they will not be able to take advantage of the reductions in disclosure. In addition there is no current proposal to move the charity audit threshold upwards, although the ICAEW appealed in March 2024 to the Minister for Civil Society for this to be reviewed.
However, company subsidiaries within small charitable groups may be able to take advantage the audit exemption available to small entities, where the charitable group is now defined as small within the revised limits.
A transitional provision is included in respect of these amendments. The effect is that when considering qualification as a particular company size by reference to a previous financial year, the amendments made by these regulations are treated as having applied in those previous years.
As a result companies and LLPs can benefit from the new thresholds as soon as possible after the legislation comes into force.
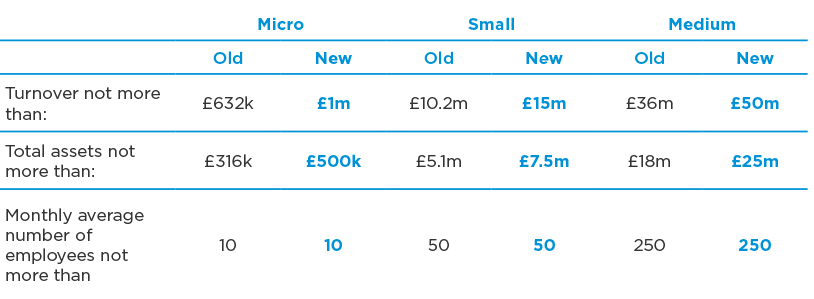
The table below sets out the new size thresholds that will apply for a financial year if any two of the three criteria are met.
Large and medium sized entities will no longer have to include in their directors’ report information on:
Please note that this content is not intended to give specific technical advice. It is designed to highlight some of the key issues rather than provide an exhaustive explanation of the topics. Professional advice should always be sought before action is either taken or refrained from as a result of information contained herein.
With over 30 years experience in the charity and not for profit sector, Nikki has provided audit services, accounting and governance support previously with PwC and Deloitte, where alongside her audit portfolio she led the technical update and charity accreditation training for the national charities and not for profit group.

Get in touch
with us.
Please submit this form and our team
will be in touch.
If your enquiry is about careers/work experience opportunities, please contact recruitment@pem.co.uk.
Cambridge HQ
Salisbury House, Station Road,
Cambridge CB1 2LA
Cambridge North
Winship House, Winship Road, Milton,
Cambridge CB24 6AP
For general enquiries
Email: hello@pem.co.uk